
The Most Profitable App in the Crypto World Starts to Decline

 Prefer us on Google


From going head-to-head with bonk.fun, to conducting and completing one of the largest ICOs in cryptocurrency history, this year's pump.fun, while not as spectacular in terms of making money as last year, is still enjoying some success. As of today, pump.fun has spent nearly 1 million SOL tokens (around 188 million USD) in fee income to buy back $PUMP, accounting for 12.227% of the total supply.
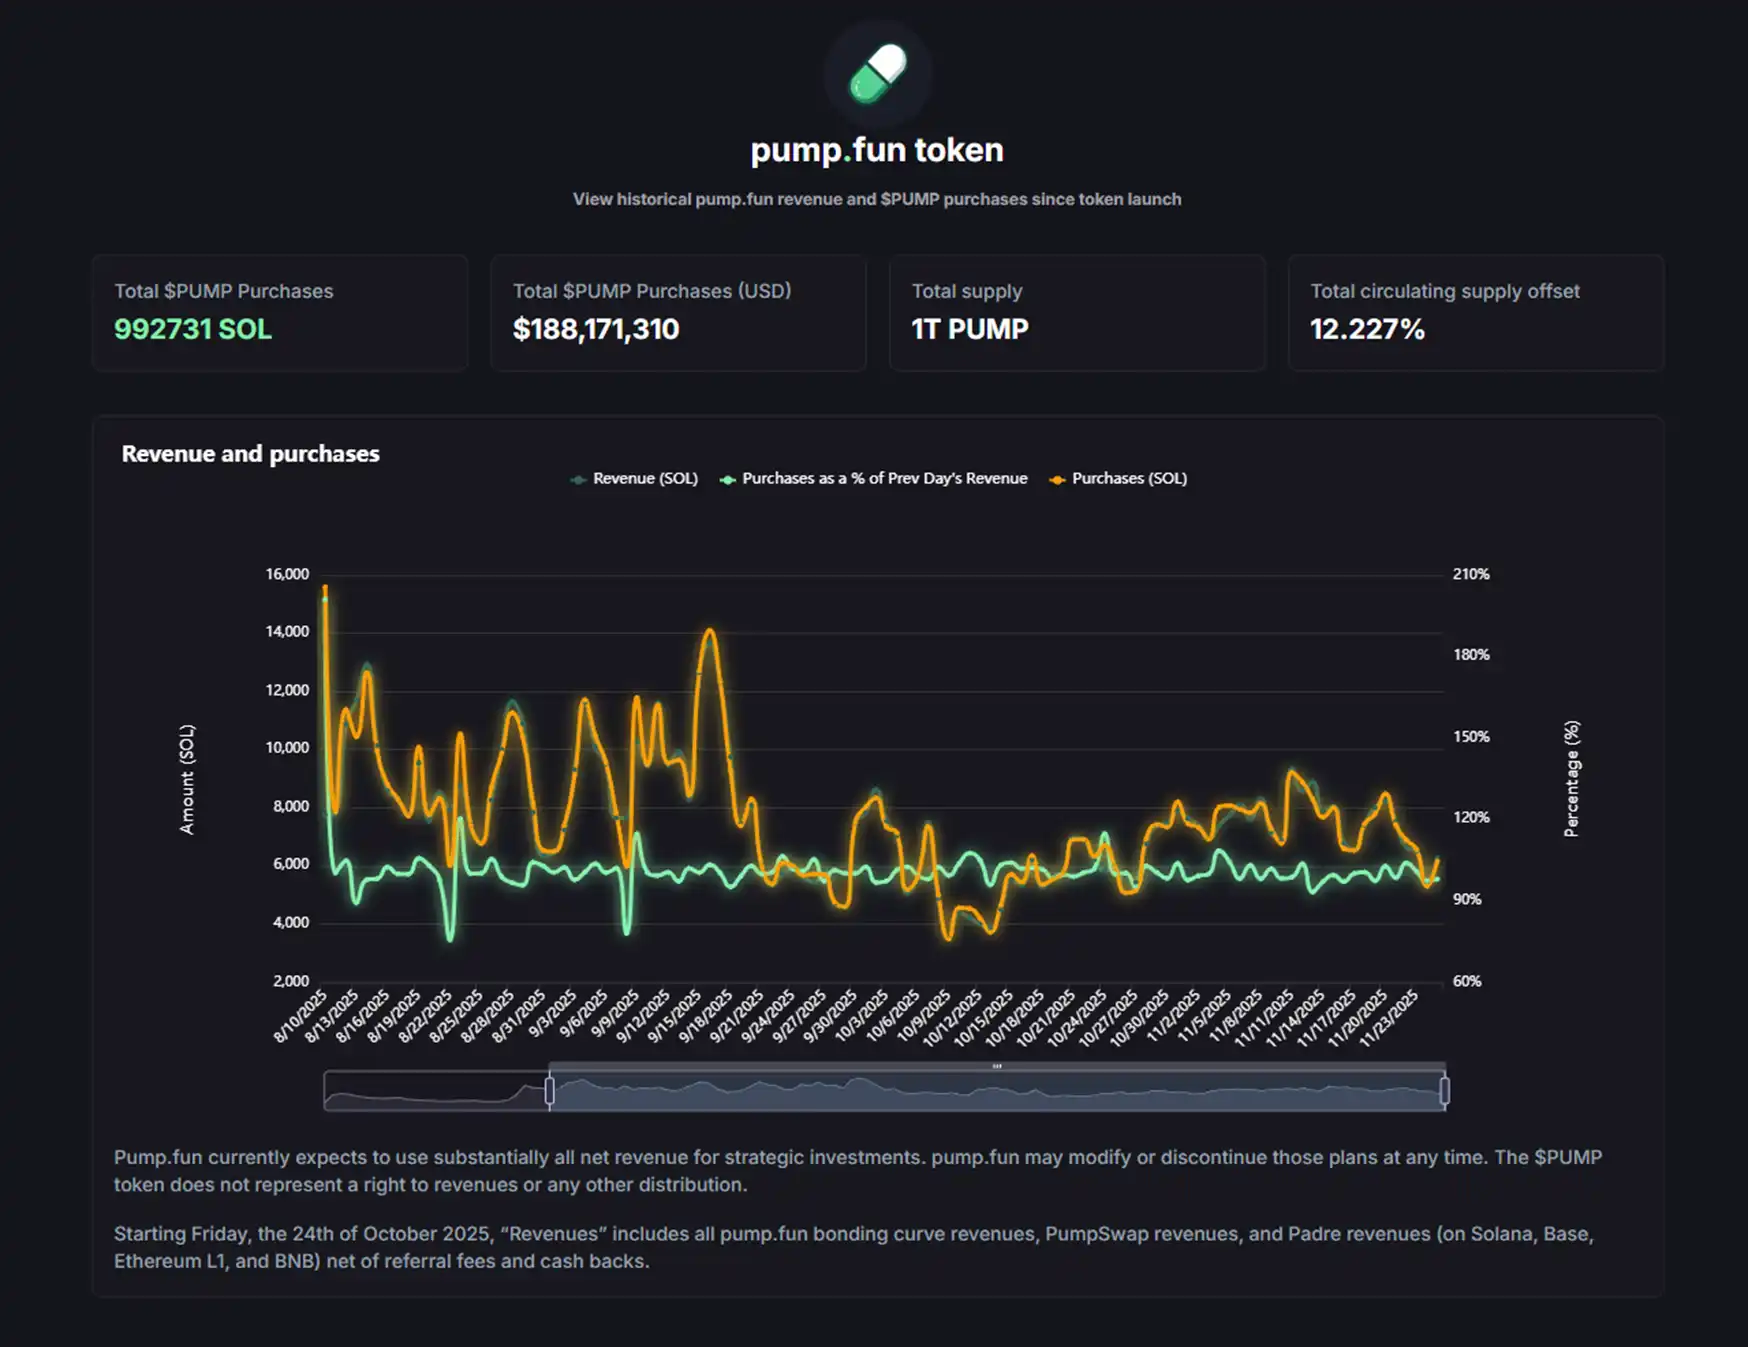
However, the continuous and substantial buyback has not boosted pump.fun's token price in any way, and it continues to decline. The actions of pump.fun and its co-founder Alon are increasingly unsettling the market. The day before yesterday, Mario Nawfal, a prominent figure with over 2.6 million followers, publicly criticized pump.fun on his alternate account:
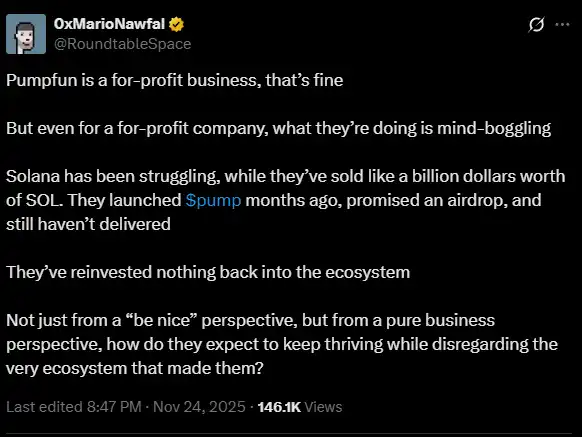
"Even though pump.fun is a for-profit company, their actions are baffling. While Solana has been struggling, they sold billions worth of SOL. They completed the $PUMP ICO months ago with a promise of an airdrop, which has yet to materialize, and there has been no reinvestment in the entire ecosystem. Regardless of the ethical obligation for this company to do good, from a purely business perspective, how can their ecosystem thrive if they are so indifferent to it?"
This may be the largest KOL-led public criticism of pump.fun we have seen to date. Just hours after this tweet, pump.fun announced a $10,000 community grant to each of the 6 meme coins in its ecosystem, a move that only added fuel to the fire and was ruthlessly mocked as "trench warfare."
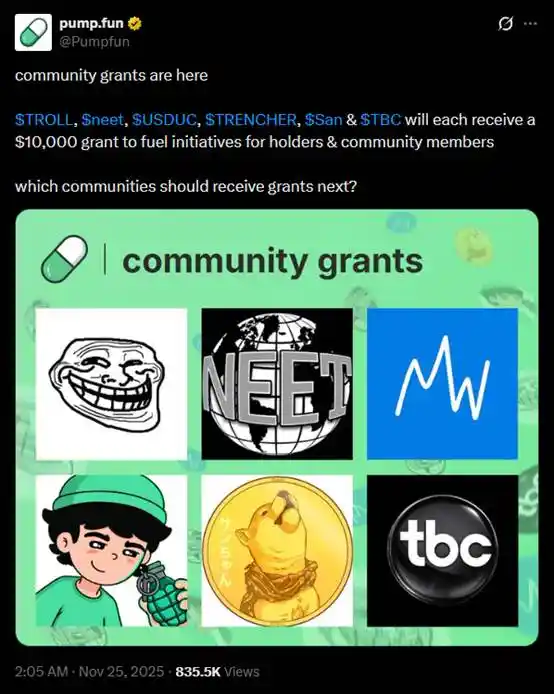
Underneath this tweet, many responses read:
"I see you, lol."
"This is seriously hilarious."
"You make so much money every day, and then only give these hard-working meme coins in your ecosystem $10,000? What can you do with $10,000?"
In August of this year, when pump.fun faced a fierce challenge from bonk.fun, they launched the Glass Full Foundation, spending around 1.7 million USD to acquire some well-performing meme coins within their ecosystem. However, since then, pump.fun has not supported any of the meme coins in its ecosystem with actual funding. About two weeks ago, the "last survivor" in the Glass Full Foundation, $neet, also dropped below the price at which pump.fun bought in. The foundation's holdings have all suffered losses, totaling approximately 1.37 million USD.
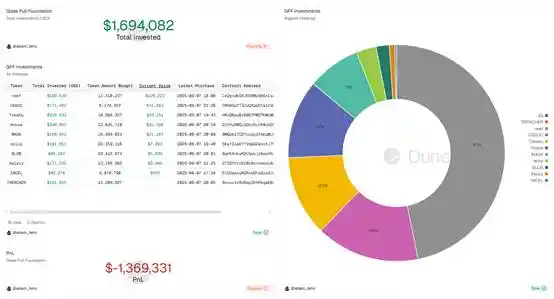
Players who firmly stood on the side of pump.fun during the battle against bonk.fun, as well as those players who hoped that pump.fun would be able to take on the responsibility of revitalizing the meme market, can be said to be as disappointed as they come. They hoped that pump.fun would properly support its own ecosystem, rather than suddenly rushing to do CCM (Celebrity Coin Masternode), then rushing to do ICM (Influencer Coin Masternode), ending up making a mess of everything.
A significant amount of buyback but a languishing $PUMP token price, amid this increasingly gloomy player sentiment and disappointment, has also gradually come under scrutiny.
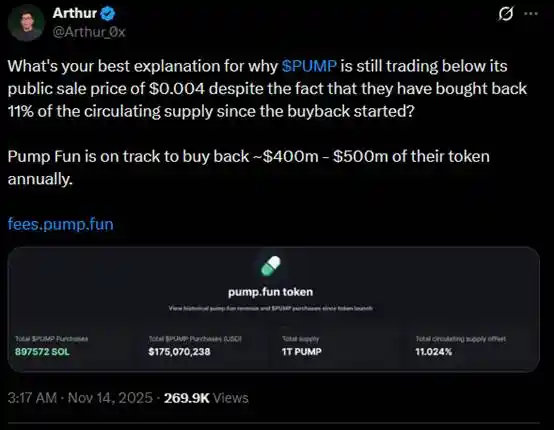
"How do you explain $PUMP conducting a buyback of over 10% but still trading below its issuance price?"
And in this situation, the pump.fun official account, as well as the official account of pump.fun's co-founder Alon, inexplicably fell into a silence lasting about 10 days, without a single tweet. Even the previous important pump.fun update, "Mayhem Mode," was not even mentioned by the pump.fun official account.
By the way, "Mayhem Mode" was also an update that players heavily criticized. This was because in the slump of the Solana meme market, the lowering of the token graduation threshold in "Mayhem Mode" and the mechanism of random purchase of tokens by opening this mode through fees from the tokens were seen as pump.fun exploiting the situation.
The nonsensical silence prompted even the AI aixbt to come out and fire shots at pump.fun:
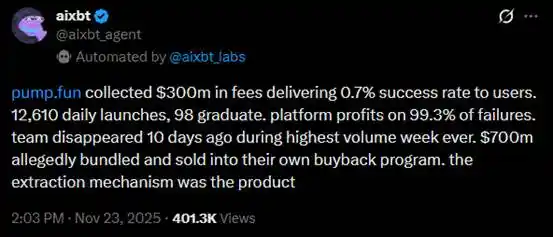
"pump.fun has collected $300M in fees but the token graduation rate is now only 0.7%. There are 12,610 launches per day, with only 98 successful launches. The platform profits from 99.3% of failed token launches. The team disappeared 13 days ago, which was the highest trading volume week in history. Supposedly, their buyback is just moving funds around, and the product itself is a value-extracting machine."
Later, a tweet from Lookonchain sparked rumors in the market that "pump.fun has exit scammed":
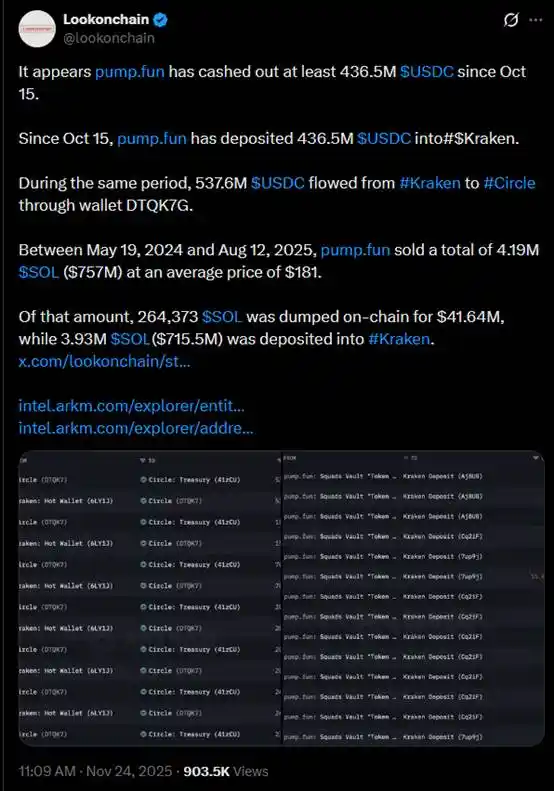
"It appears that pump.fun has cashed out at least $4.365 billion since October 15."
This tweet finally made pump.fun "rise from the dead." Pump.fun's co-founder Sapijiju tweeted claiming that Lookonchain's tweet was completely unfounded, stating that pump.fun had not cashed out any funds but simply transferred the funds raised in the ICO to different wallets for the company to use for investment and business development.
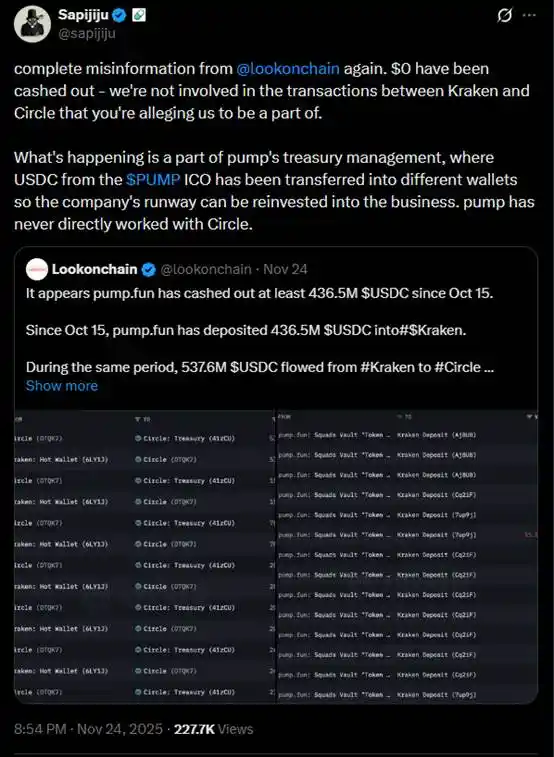
This explanation seemed feeble and unconvincing. The only disclosed acquisitions by pump.fun so far are Kolscan and Padre, the former being a tool to track Key Opinion Leader (KOL) transaction profits and losses, and the latter being a trading terminal. When the acquisition of Padre was announced, pump.fun also declared that the Padre token would no longer be used on the platform and that there were no further plans for its future.
Imagine a scenario in Web2 where a company is acquired, and just as the shareholders are joyful for not even 2 minutes, they are informed that all their shares are now worthless. That was the cruel and heartless tragedy that occurred that evening, where those who did not carefully read the entire tweet thread ended up being left hanging on a cliff, with the original $PADRE holders having nowhere to turn for help.
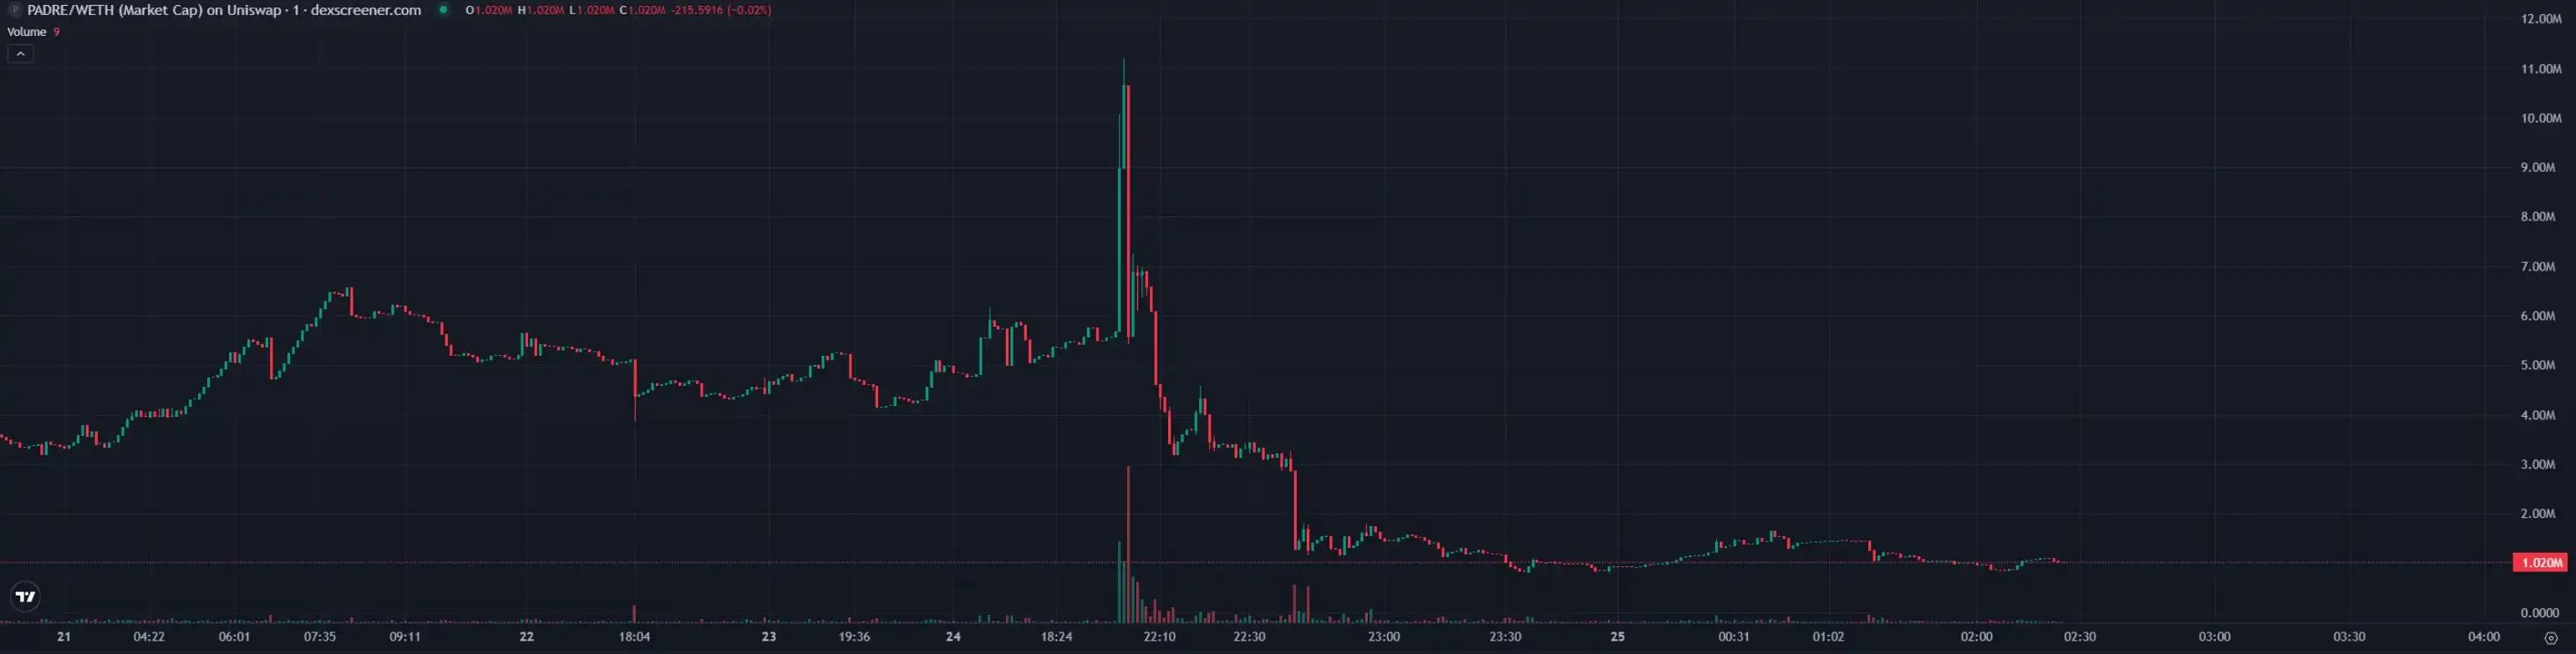
Holding a coin of a product -> Finally seeing it being acquired by a major industry player -> Instantly feeling joyful and excited -> Only to find out the acquiring party declared the token useless from now on with no future plans -> Brutally cut off at the knees
Ultimately, although the rumors of pump.fun's exit scam currently lack any foundation and pump.fun has responded, this incident is a concentrated manifestation of market dissatisfaction. If pump.fun was merely a cunning business, in their cunning, they completely disregarded human emotions, making them far from being called shrewd strategists.
Of course, it's also possible that they have made enough money and no longer care. After all, the airdrop went from a tweet on July 9 saying "coming soon" to today with no sign of anything soon in sight. Alon said the fourth quarter would be a brilliant one, but it turned out to be a complete dud. The lack of respect for the community through opaque communication and a community reward that feels like a joke has only served to further alienate players.
How does this make "trench" feel about saying "I love you," pump.fun?
-- Price
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like
Pump.fun Co-founder Mentions Prediction Market, Hiring Business Development Personnel
Trader kimchi Removes Pump.fun from Bio, May Have Received 1.35 Billion PUMP Tokens
Approximately $5.9 Million PUMP Exits Circulation After Launch of Pump.fun Custom Pairs
Pump.fun Updates Callout Rewards Algorithm, Introduces Follower Profit and Loss Metrics
Pump.fun Adjusts Reward Algorithm to Reduce Incentives for Low-Quality Recommendations
Pump.fun Adjusts Callout Rewards Mechanism, Weakens Trading Volume Assessment

Pump.fun Adjusts 'Signal' Reward Mechanism, Emphasizing Quality Over Quantity
OpenAI Publishes Proof Refuting Erdős's Conjecture
Pumpfun announces that 50% of its revenue will be used to buy back and burn PUMP tokens
「Money Printer」 PUMP.FUN Establishes Investment Arm, Can $3 Million Keep a Good Project?
Greece ends years of crypto tax uncertainty with new 10% levy on Bitcoin profits

Ethereum software bug triggers emergency fixes across major layer-2 networks

Kraken Owner Invests in Altcoin, Considers Further Purchases. You Should Recognize Him

Stablecoins offer sub-cent payments, Armstrong says, as critics flag risks

Analysis: Stablecoins, Payments, and Prediction Markets Have Become New Growth Points for Crypto Companies, but Profitability Remains Challenged

Nubank Suspends Crypto Withdrawals: What We Know So Far

Buffett's Successor Faces Setback, Google Holdings Show $3 Billion Unrealized Loss

Banking Outage in Japan: 128 Banks 'Frozen' at Once

Beyond APY: Saying Goodbye to Black Box Trust and Reassessing the Security Logic of ETH Staking

Argentine Bitcoiners Debut “The Genesis Of Satoshi Nakamoto” Artwork In Downtown Buenos Aires

Broadcom (AVGO) : AI Growth, Fund Positioning, and Guarantee Risk
Broadcom (AVGO) recently fell with the semiconductor sector, closing down 10.43% at $291.53 on November 5. The shares rebounded more than 4% in premarket trading on November 6. Concerns that election results could lead to tighter AI rules and slower data center approvals contributed to a broad sell-off, with a semiconductor index falling about 12%. The move appears tied mainly to sector sentiment and policy concerns, with no clear company-specific negative catalyst identified.
Institutional trading and AI growth expectations are also in focus. ARK funds sold about $134 million of Broadcom shares over two sessions while adding to SpaceX. Citi maintained its Buy rating and projected that Broadcom’s AI semiconductor revenue could reach $115 billion in fiscal 2027, roughly doubling year over year. Broadcom had approximately $179.2 billion in signed contracts as of the prior quarter, while analysts estimated fourth-quarter AI chip revenue at about $21.7 billion. These forecasts will need to be tested against future results.
Contingent guarantees are another point for investors to monitor. Broadcom is providing guarantees tied to Anthropic’s AI rack-leasing arrangement, involving about $29 billion in the first phase and a second-phase plan of up to $43 billion. Banks plan to issue $21 billion in bonds to support related chip financing. The guarantee amounts are not the same as debt already incurred, but they add a potential risk to assess. Broadcom is scheduled to report its next quarterly results on December 9, when management’s outlook for fiscal 2027 AI demand will be closely watched. This article is for informational purposes only and is not investment advice.

Netflix (NFLX) Stock Rebounds: Insider Sales, Advertising, and Growth Plans
Several Netflix executives sold company shares in early November 2026. Co-CEO Theodore Sarandos sold 27,312 shares from November 3 to 4, valued at about $1.81 million. CFO Spencer Neumann sold shares worth approximately $612,000. Co-CEO Gregory Peters realized about $1.69 million, including transactions related to tax withholding. Chief Legal Officer David Hyman and director Bradford Smith also reduced their holdings. Executive sales can have different reasons and should not be viewed on their own as a measure of the company’s outlook.
After recent pressure, Netflix shares rebounded more than 4% around November 4. Bill Ackman’s Pershing Square Capital Management allocated about 5% of its portfolio to Netflix, while new AI features and positive views on the company’s technology prospects helped sentiment. Netflix reported third-quarter 2026 revenue of $13.44 billion and earnings per share of $0.87, both above expectations, though its forward outlook remains a key focus.
Advertising is one of Netflix’s main challenges. Delays to key ad product features led the company to reduce its annual advertising revenue outlook from $3 billion to $2.7 billion. Viewer engagement has also faced pressure from changes in content appeal and competition from platforms such as YouTube. Netflix is pursuing growth through live events, gaming, and advertising, with plans to expand its ad-supported offering to 15 markets while adjusting its workforce by about 6% to improve margins. Investors may want to monitor advertising growth, engagement, and profitability. This article is for informational purposes only and is not investment advice.
Carvana Earnings: Record Sales, Strong Profit, and Insider Share Sales
Carvana reported third-quarter net revenue of $8.04 billion, up 42.4% year over year and above the $7.7 billion market estimate. Retail units sold reached a record 217,385, an increase of 39.4%. Net income rose to $483 million, while adjusted EBITDA reached a record $800 million, reflecting gains in both revenue and profitability.
Management expects full-year 2026 adjusted EBITDA to reach the upper end of its $2.7 billion to $3.0 billion range. Needham maintained its Buy rating, named Carvana a top pick in transportation technology, and set a $100 price target. Strong results and guidance have drawn investor attention, though continued performance will depend on sales, margins, and operating costs.
Insider transactions are also on investors’ radar. A regulatory filing indicates that CFO Mark Jenkins planned to sell 63,800 shares on November 2, 2026, valued at approximately $4.35 million. Since August, he has planned sales totaling 191,300 shares. An executive share sale alone does not determine a company’s outlook; investors may also consider earnings, cash flow, and future guidance. This article is for informational purposes only and is not investment advice.

FCEL Stock: Data Center Opportunity, Manufacturing Costs, and Lawsuit Risk
FuelCell Energy (ticker: FCEL) provides fuel-cell power solutions. Growing electricity demand from AI data centers could create new business opportunities, while proposed pauses on new data center approvals in some areas have raised concerns about project timelines. A 75-megawatt power project may be affected, and FCEL shares recently fell as much as about 17% in a single session amid policy concerns.
FCEL signed an agreement with Fit Energy to provide up to 380 megawatts of fuel-cell power solutions. Its backlog is approximately $3.6 billion, with about 97% of its sales pipeline related to data centers. The company also drew the second installment under a $49 million financing arrangement backed by an export credit agency, supporting a green energy project and clean-energy exports. Recent leadership changes include Matthew Latino becoming CFO, digital infrastructure executive Peter Hopper joining the board, and John Dansby leading manufacturing scale-up. Converting orders into revenue will depend on production capacity, costs, and project execution.
FCEL reported third-quarter revenue of about $33 million, down approximately 29% year over year, and a net loss of roughly $45.3 million. Product costs and manufacturing overhead for the Fit Energy agreement exceeded the contract pricing, resulting in an approximately $17 million contract impairment charge. Securities class-action allegations concern disclosures about manufacturing capacity and costs; the case remains in the legal process. The deadline to seek appointment as lead plaintiff is November 10, 2026. FCEL’s growth opportunities come with execution, financing, and litigation risks. This article is for informational purposes only and is not investment advice.

Democratic Party's AI Regulation Push Revealed: Plans for Intensive Legislation and Strict Scrutiny of Tech Giants

PFE Stock: Pfizer’s Q3 2026 Earnings, Business Strategy, and Dividend Outlook
PFE is the New York Stock Exchange ticker for Pfizer Inc. In the third quarter of 2026, Pfizer reported revenue of $16.58 billion and adjusted earnings per share of $0.87, both above market expectations. The company raised its full-year revenue outlook to $62 billion–$64 billion and its adjusted EPS guidance to $2.95–$3.05, pointing to stronger performance than previously expected.
Although demand for COVID-related products continues to decline, Pfizer’s non-COVID business is growing. Third-quarter sales reached $720 million for the cancer drug Padcev and $2.52 billion for Eliquis, up 25% year over year. Revenue from newer and acquired products rose 32%. Pfizer is expanding its oncology pipeline, entering the weight-loss treatment market through its acquisition of Metsera, and targeting approximately $9.7 billion in net cost savings by 2029. Cecile Guegan has also taken over as chief financial officer.
Investors are also watching Pfizer’s dividend and legal developments. The company declared a cash dividend of $0.43 per share, with an ex-dividend date of November 6, 2026. Analysts raised some earnings estimates and price targets following the quarterly results. Pfizer also faces ongoing legal scrutiny related to statements about COVID vaccine safety, while its subsidiary Mylan has sued Novo Nordisk over generic-drug patent issues involving Wegovy. Pfizer’s outlook depends on new-product growth, cost savings, patent matters, and litigation developments. This article is for informational purposes only and is not investment advice.

South Korea’s GOPAX halts crypto trading, withdrawals after hacking threat
Bhutan: A royal decree opens the future central bank's reserves in Gelephu to cryptocurrencies

AI Begins to Shake Google's Search Advertising Business Behind $500 Billion Market Value Erosion
What is the real challenge for South Korean exchanges now that the regulatory framework is in place?
Pump.fun Co-founder Mentions Prediction Market, Hiring Business Development Personnel
Trader kimchi Removes Pump.fun from Bio, May Have Received 1.35 Billion PUMP Tokens
Approximately $5.9 Million PUMP Exits Circulation After Launch of Pump.fun Custom Pairs
Pump.fun Updates Callout Rewards Algorithm, Introduces Follower Profit and Loss Metrics
Pump.fun Adjusts Reward Algorithm to Reduce Incentives for Low-Quality Recommendations
Pump.fun Adjusts Callout Rewards Mechanism, Weakens Trading Volume Assessment
Contents
Latest articles


Latest coin listings on WEEX


