
Market Downturn: Which Assets Are Worth Watching?

 Prefer us on Google


Original Title: The「Investible」Crypto Tokens
Original Author: Ignas, DeFi Analyst
Original Translation: Saoirse, Foresight News
CoinGecko tracks 17,148 tokens.
But in the current crypto market environment, how many tokens truly meet the following criteria to be considered 「investible」?
1. Can provide returns to the holder;
2. Have protocol revenue, even if not yet distributed;
3. Strong narrative and market recognition to survive a bear market.
I tried to figure this out.
Most of the data is from DefiLlama, CoinMarketCap, and some protocols reflecting market heat (Dexu, Moni, Lunarcrush, etc.).
I used Claude Code to process the data, trying to minimize personal bias—
I would have originally excluded some tokens (such as XRP, ADA, BCH, etc.), but they have gone through multiple cycles and have sustained vitality due to sufficient liquidity.
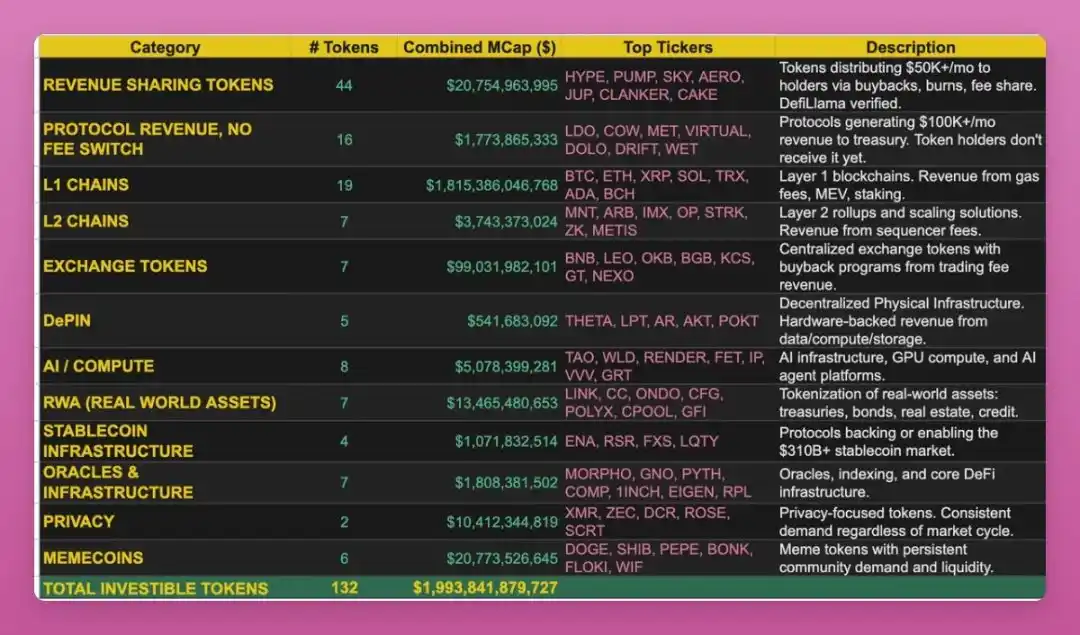
Claude still made many mistakes, and debugging took 10 times longer than writing the article, so the tabular data is for reference only (link at the end of the article).
Final Results:
· A total of 12 categories, 132 investible tokens were filtered;
· Among them, 45 tokens provide dividends to holders (excluding those with very low returns);
· Annualized returns to holders: $1.8 billion.
These classifications are entirely based on my subjective judgment of 「survivability and future potential,」 which you may disagree with.
First Key Finding: The truly investible crypto market is tiny.
And tokens that can actually make holders money are almost monopolized by two projects. Details will follow below.
It's funny that, in the process of organizing this list and checking each token one by one, I came to this conclusion:
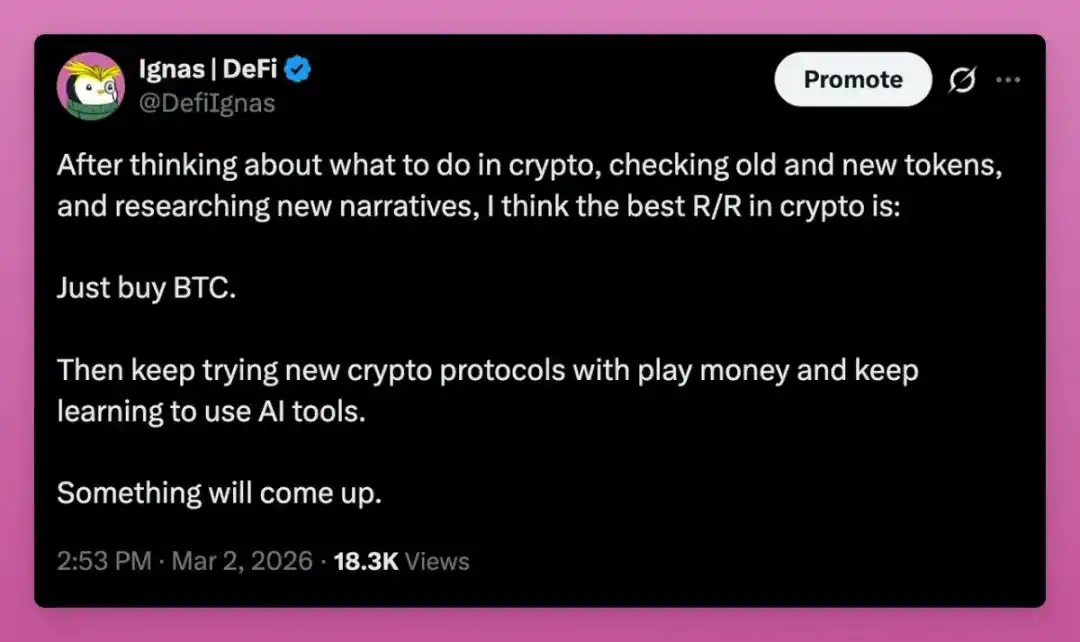
After much consideration on how to navigate the crypto space, reviewing old and new tokens, and researching new narratives, I believe the most optimal risk-reward ratio (R/R) in the crypto world is:
Directly buying Bitcoin (BTC).
Then using "play money" to continuously try out new crypto protocols while consistently learning to use AI tools.
New opportunities will always arise.
Most Investment-Worthy Token: Revenue-Sharing Category
The current market's mainstream narrative is:
A project without revenue will eventually die!
Even ETH finds it hard to escape this "value by revenue" narrative.
Therefore, the most investable tokens are those that can distribute revenue to holders through buybacks, burns, fee sharing, etc.
I've set the threshold at: DefiLlama 30-Day Holder Revenue ≥ $50,000.
These 45 tokens bring holders $153 million in revenue monthly,
with a total annualized revenue of $1.8 billion.
Top 10 Revenue Shares:
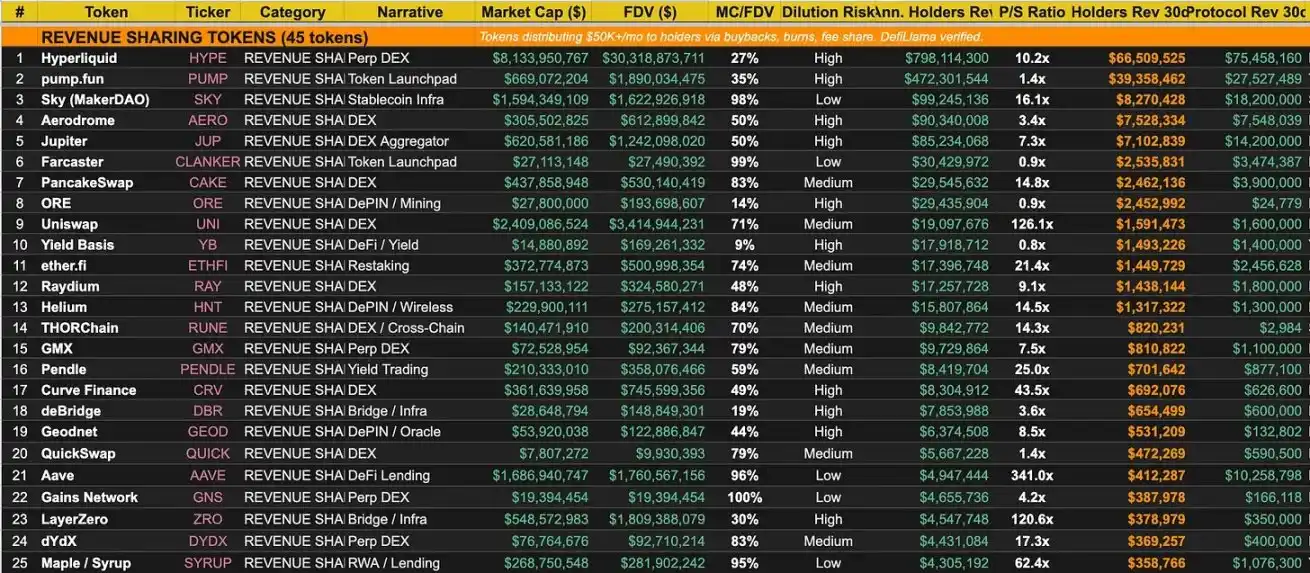
Note: Revenue share ≠ Holder revenue on DefiLlama.
For example: EtherFi doesn't make the holder revenue list, but it has buybacks.
L1 chains like Tron have been categorized separately.
After the top five, monthly revenue quickly drops to below $3 million.
If the crypto market continues toward the logic of "tokens = stocks,"
So the P/S (Price-to-Sales, Market Cap / Revenue) ratio will become increasingly important.
· Pump.fun: 1.4x
· Aerodrome: 3.4x
By traditional financial standards, these are extremely cheap.
Based on current revenue pace, the entire market cap could be recouped in less than 3 years.
However:
· Uniswap: P/S as high as 121x
· Aave: P/S even at 341x
Because the market has valued them far beyond "current returns."
Aave recently started buybacks finally, distributing only $412k per month, whereas the protocol generates $10m in monthly revenue. Subsequent governance changes could alter this.
Lowest P/S Ratio Tokens:
· Farcaster's Clanker: 0.9x
· ORE: 0.9x
· Yield Basis: 0.8x
· Pump.fun: 1.4x
· QuickSwap: 1.4x
All of these could recoup their market cap in 3 years based on revenue.
Key Takeaway:
Hyperliquid + Pump.fun = 69% of total holder revenue!
Among 45 tokens, only two projects contribute over 2/3 of the cash flow.
This level of concentration is very worth considering.
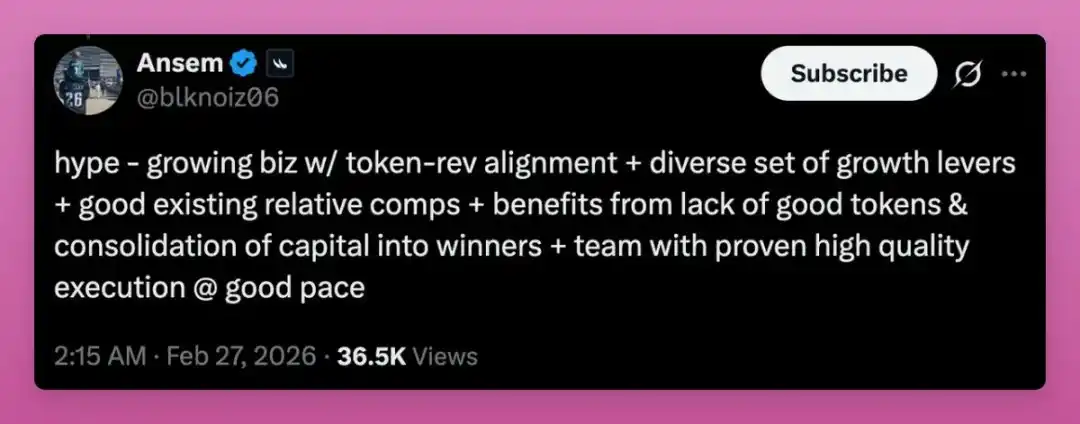
Ansem's tweet nicely summarizes the HYPE investment thesis:
HYPE:
· Business on a growth trajectory, with token closely tied to revenue;
· Possessing diversified growth levers;
· Existing comparable projects perform well;
· Benefit from a market environment with high-quality token scarcity and funds flowing to top projects;
· Strong team execution, steady pace, and impressive track record.
Has Protocol Revenue, But Has Not Enabled Dividends
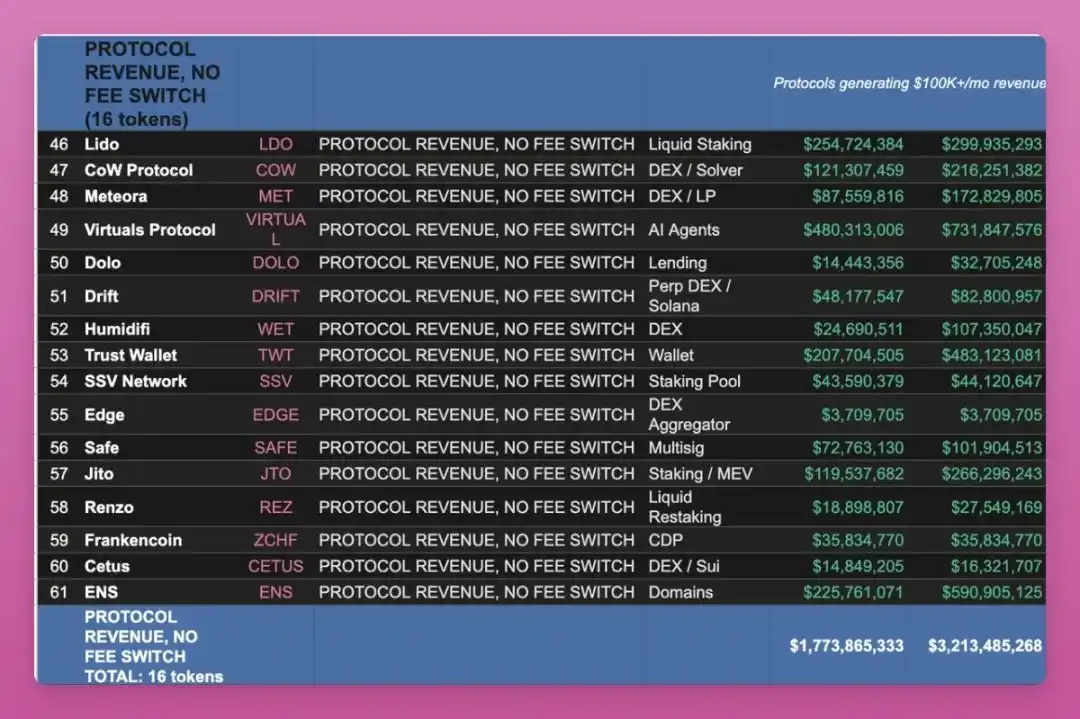
This category consists of 16 tokens, with monthly protocol revenue ≥ $100,000, which is retained in the treasury.
Top Projects:
· Lido: $4.3 million per month, TVL $32 billion (previously proposed staking dividends last year);
· CoW Protocol: $3 million per month;
· Meteora (Solana): $2 million per month;
· Virtuals Protocol: $1.4 million per month;
· Drift: $868,000 per month.
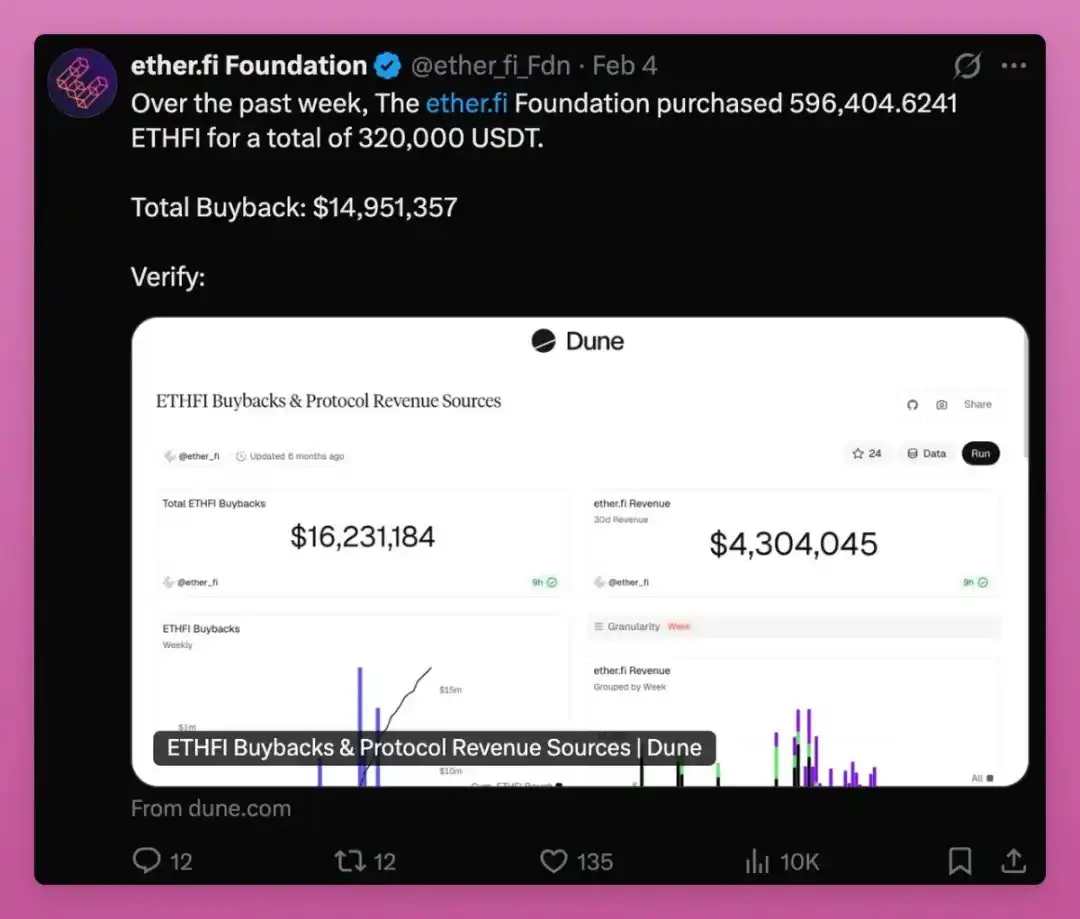
The comparison between Lido and ether.fi is quite interesting:
· Lido has a TVL that is 10 times higher and revenue that is 3 times higher, but LDO holders don't receive a cent;
· ether.fi distributes $1.5 million to holders monthly through buybacks.
If you were to go through a bear market, you would want to be with the one that can give you money.
The investment logic for these targets is:
These protocols will sooner or later enable the "dividends switch."
Lido has been talking about it for many years.
Jito has total monthly fees of $5.3 million, but only $544,000 enters the treasury.
The gap between total fees and holder earnings is both an opportunity and a risk.
Overview of Other Sectors
Exchange platform tokens (7 tokens, total market value $990 billion, including BNB)
You can make money regardless of market conditions. CEX trading volume may decrease, but it will not go to zero.
· BNB: $850 billion;
· LEO, OKB hardly dropped during the 2022, 2024 bear markets.
Many have buyback programs, just not reflected in DefiLlama data.
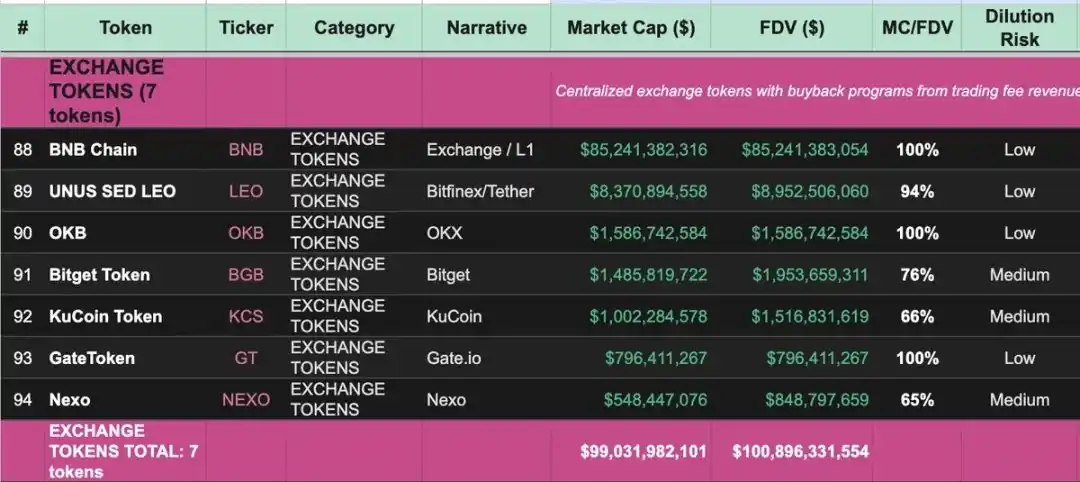
CEX tokens have a high circulation ratio, further reducing downside risk.
L1 Blockchains (19, total market cap $1.8 trillion)
L1 is the base layer.
· BTC: $1.36 trillion
· ETH: $245 billion
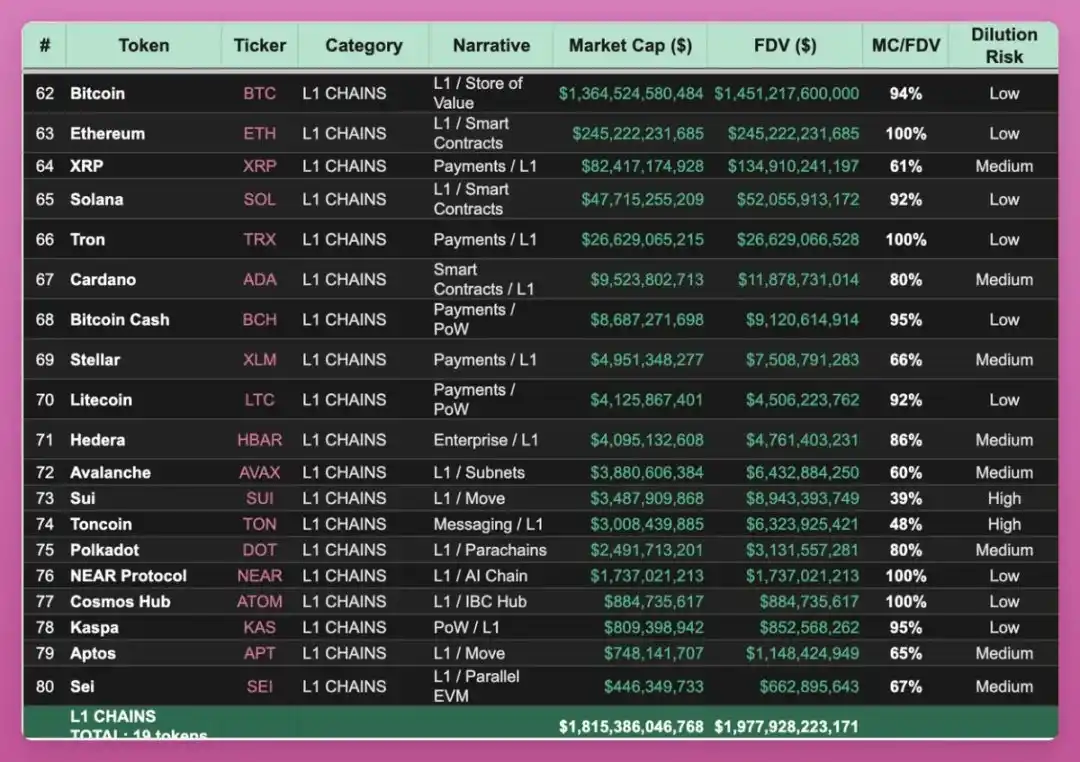
I have relaxed standards for XRP, ADA, especially Cosmos, as they have survived multiple cycles, have believers and liquidity, and demonstrate enduring vitality.
You may dislike TRON TRX, but it generates $26 million in monthly fees—more than Solana and Ethereum.
It has also shown strong performance this cycle; you can check the candlestick chart yourself.
L1 blockchains will not disappear, but valuation fluctuations will be significant. Trade at your own risk.
AI & Computing (8, total market cap $5.1 billion)
Most have no actual revenue, except for one:
Venice (VVV): The only AI token supported by subscription and API revenue for buyback and burn, with 43% of the supply already burned.
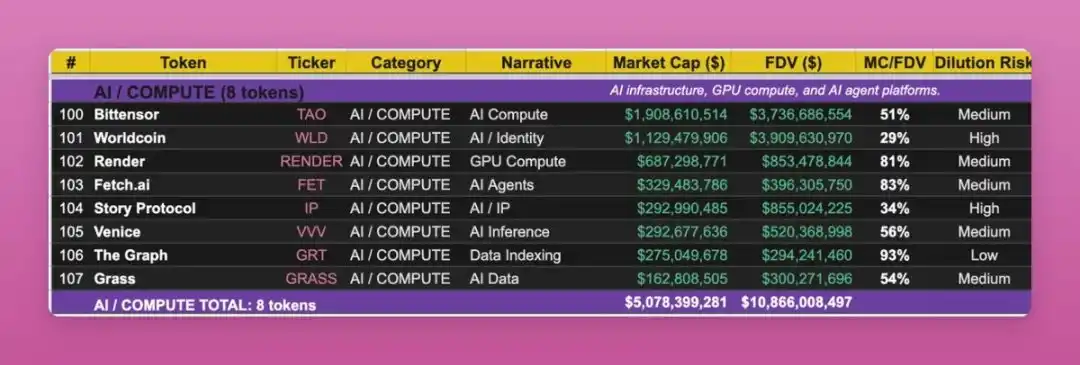
· Bittensor: $1.9 billion market cap, 128 subnets, no protocol revenue;
· Render, Akash: Sell GPU computing power cheaper than centralized platforms;
· Grass: Provides decentralized network data for AI training.
Note: Some AI tokens not listed are currently experiencing a surge and may be suitable for short-term trading, but whether they are "investable" is debatable.
RWA Asset Tokenization (7, total market cap $13.5 billion)
Growing quietly, I believe the real RWA bull market has yet to come.
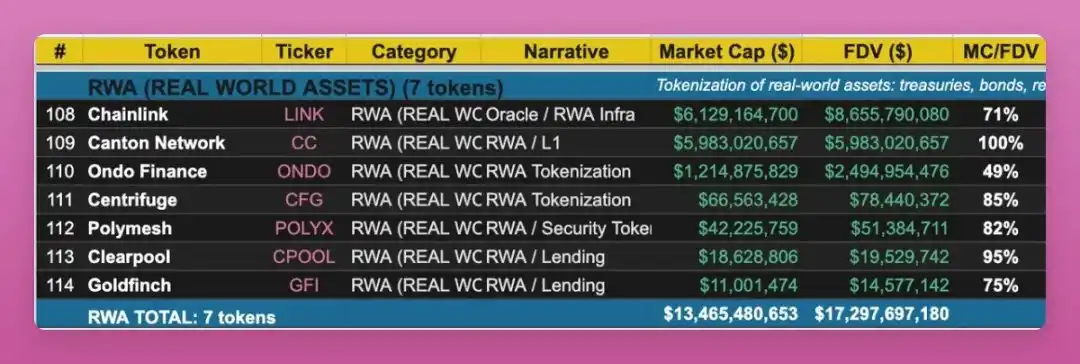
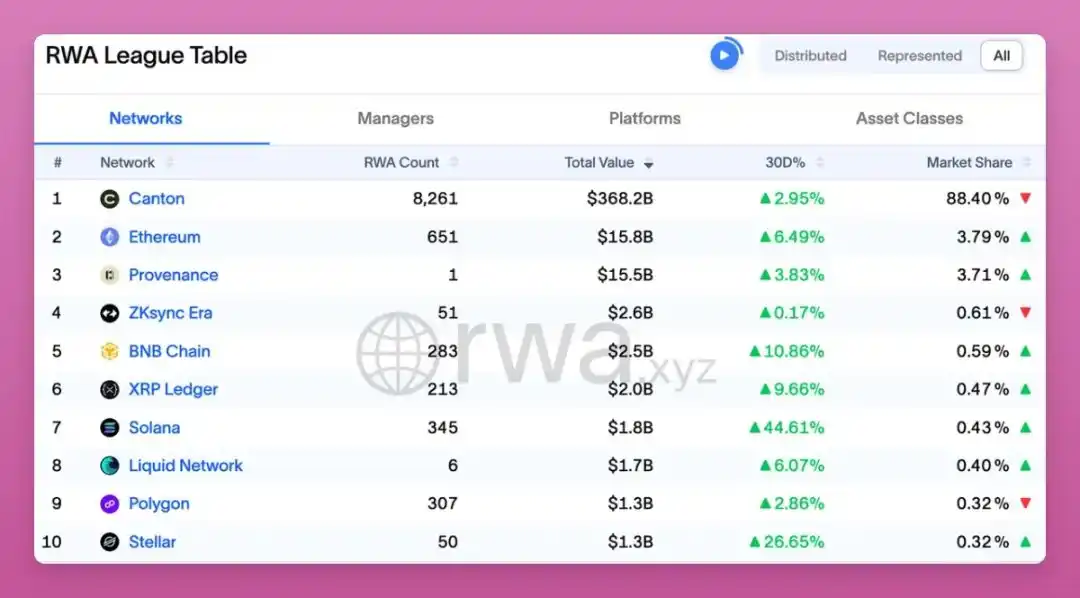
The Canton Network holds 88.57% of on-chain RWA, approximately $372 billion in tokenized assets. However, real-world assets are not as simple as they may seem on the surface.
Chainlink is the key oracle for RWAs, but LINK staking rewards come from inflation and a fixed reward pool, not protocol revenue sharing.
Chainlink revenue is solid, but flows to node operators and the treasury, not directly to holders.
Privacy Coins (2, total market cap $97 billion)
High-risk track: either increasingly important with tightening regulations or outright bans.
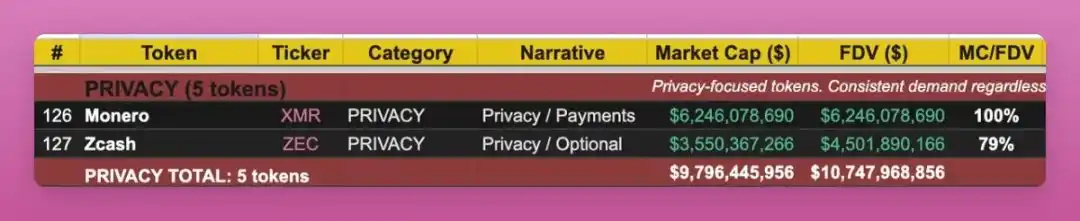
But regardless of the bull or bear, the demand remains stable.
· Monero: $6.2 billion
· Zcash: $3.6 billion
Meme Coins (6, total market cap $208 billion)
Categorizing them as "investable" may be controversial.
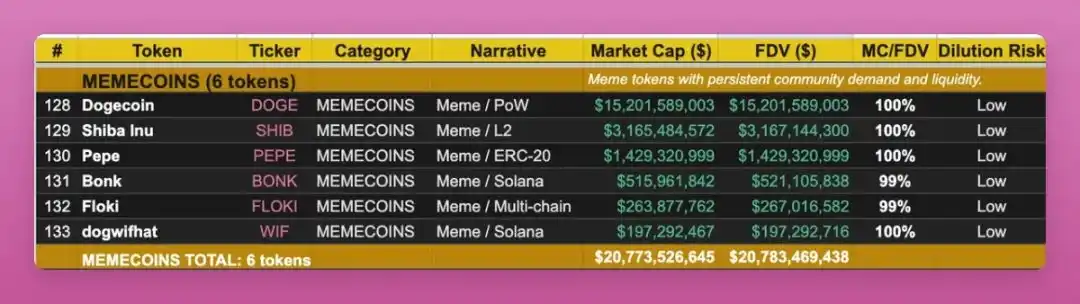
But like Bitcoin, they survive on community.
· DOGE: $15.2 billion market cap, in existence for over a decade;
· SHIB, PEPE, BONK, FLOKI, WIF are also on the list.
If the market rebounds, they may outperform high-yield tokens.
Because there is no income ceiling, there is no cap either.
And they are almost all in circulation, with little selling pressure.
Other Categories
· L2 Chains (7, total market cap $37 billion);
· DeFi Protocols (5, total market cap $5 billion): decentralized storage, data oracles;
· Oracles / Infrastructure (7, total market cap $18 billion);
· Stablecoin Infrastructure (4, total market cap $11 billion): Ethena leading.
-- Price
Super Profitable Projects Without Tokens
Some of the most profitable crypto businesses have no investable tokens at all.
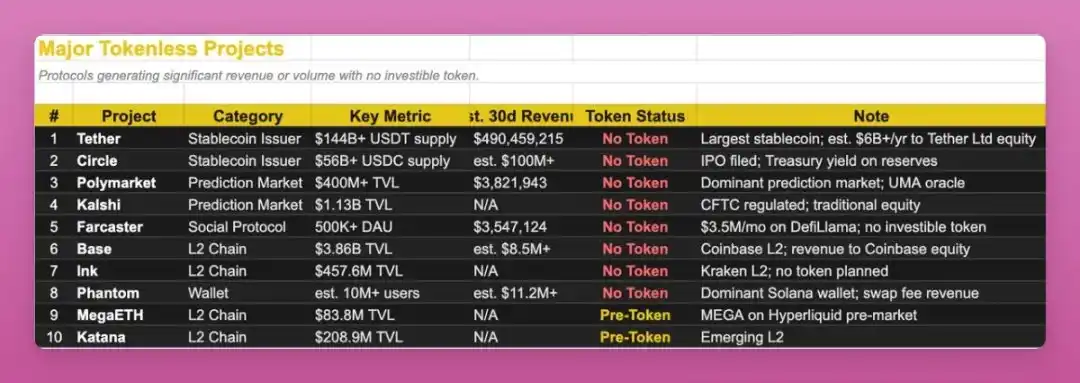
· Tether: Annual revenue of over $6 billion, more than the sum of those 45 income tokens, all go to shareholders;
· Polymarket: Monthly revenue of $3.8 million, no native token;
· Base: Revenue goes to Coinbase shareholders, potential future token issuance;
· Phantom: Millions of users, very high fees;
· Circle: Issuer of USDC, revenue reflected in IPO;
· Kalshi: CFTC-regulated, no native token;
· Farcaster: Acquired, expected significant airdrop reduction, but possible future token issuance.
So, how to use this information?
Ideal holdings in a bear market meet four criteria:
1. Have holder revenue
2. Low P/S ratio (market cap / revenue)
3. High MC/FDV (circulating market cap / fully diluted valuation)
4. Sustained stable demand
Very few tokens meet all criteria.
Closest candidates:
· PUMP: 1.4x P/S, 33% MC/FDV
· AERO: 3.4x, 50%
· JUP: 7.3x, 51%
· SKY: 16x, 98%
· CAKE: 15.1x, 96%
Low-risk picks:
Exchange platform tokens: LEO, OKB, GT
Almost fully circulating, supported by exchange platform profit buybacks, most stable performance in a bear market.
High-risk high-reward:
HYPE: Leading in revenue but only 25% MC/FDV.
After Coingecko's new stats excluding long-term non-circulating and burned tokens, it dropped to 41%.
Trading opportunities:
Watch for governance changes:
Bet on projects with revenue but no dividend distribution yet, turn on the "dividend switch".
Key focus:
Lido, Meteora, Drift, CoW Protocol
Everything else is a matter of faith.
Do you believe in AI computation on-chain?
Do you believe RWA tokenization will continue to grow?
I believe it will, but are these tokens the right bet?
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like
Secret Network lost 4.67 million dollars due to a cross-chain vulnerability, and the attack went undetected for seven days

CoW Swap released a report on the attack incident, stating that the domain was hijacked for several hours, resulting in an estimated loss of 1.2 million dollars
A user lost approximately 50 million dollars in a single transaction due to slippage, and the founder of Aave stated that the interface had issued multiple warnings

Ethereum software bug triggers emergency fixes across major layer-2 networks

Kraken Owner Invests in Altcoin, Considers Further Purchases. You Should Recognize Him

Stablecoins offer sub-cent payments, Armstrong says, as critics flag risks

Analysis: Stablecoins, Payments, and Prediction Markets Have Become New Growth Points for Crypto Companies, but Profitability Remains Challenged
Nubank Suspends Crypto Withdrawals: What We Know So Far

Buffett's Successor Faces Setback, Google Holdings Show $3 Billion Unrealized Loss

Banking Outage in Japan: 128 Banks 'Frozen' at Once

Beyond APY: Saying Goodbye to Black Box Trust and Reassessing the Security Logic of ETH Staking

Argentine Bitcoiners Debut “The Genesis Of Satoshi Nakamoto” Artwork In Downtown Buenos Aires

Broadcom (AVGO) : AI Growth, Fund Positioning, and Guarantee Risk
Broadcom (AVGO) recently fell with the semiconductor sector, closing down 10.43% at $291.53 on November 5. The shares rebounded more than 4% in premarket trading on November 6. Concerns that election results could lead to tighter AI rules and slower data center approvals contributed to a broad sell-off, with a semiconductor index falling about 12%. The move appears tied mainly to sector sentiment and policy concerns, with no clear company-specific negative catalyst identified.
Institutional trading and AI growth expectations are also in focus. ARK funds sold about $134 million of Broadcom shares over two sessions while adding to SpaceX. Citi maintained its Buy rating and projected that Broadcom’s AI semiconductor revenue could reach $115 billion in fiscal 2027, roughly doubling year over year. Broadcom had approximately $179.2 billion in signed contracts as of the prior quarter, while analysts estimated fourth-quarter AI chip revenue at about $21.7 billion. These forecasts will need to be tested against future results.
Contingent guarantees are another point for investors to monitor. Broadcom is providing guarantees tied to Anthropic’s AI rack-leasing arrangement, involving about $29 billion in the first phase and a second-phase plan of up to $43 billion. Banks plan to issue $21 billion in bonds to support related chip financing. The guarantee amounts are not the same as debt already incurred, but they add a potential risk to assess. Broadcom is scheduled to report its next quarterly results on December 9, when management’s outlook for fiscal 2027 AI demand will be closely watched. This article is for informational purposes only and is not investment advice.

Netflix (NFLX) Stock Rebounds: Insider Sales, Advertising, and Growth Plans
Several Netflix executives sold company shares in early November 2026. Co-CEO Theodore Sarandos sold 27,312 shares from November 3 to 4, valued at about $1.81 million. CFO Spencer Neumann sold shares worth approximately $612,000. Co-CEO Gregory Peters realized about $1.69 million, including transactions related to tax withholding. Chief Legal Officer David Hyman and director Bradford Smith also reduced their holdings. Executive sales can have different reasons and should not be viewed on their own as a measure of the company’s outlook.
After recent pressure, Netflix shares rebounded more than 4% around November 4. Bill Ackman’s Pershing Square Capital Management allocated about 5% of its portfolio to Netflix, while new AI features and positive views on the company’s technology prospects helped sentiment. Netflix reported third-quarter 2026 revenue of $13.44 billion and earnings per share of $0.87, both above expectations, though its forward outlook remains a key focus.
Advertising is one of Netflix’s main challenges. Delays to key ad product features led the company to reduce its annual advertising revenue outlook from $3 billion to $2.7 billion. Viewer engagement has also faced pressure from changes in content appeal and competition from platforms such as YouTube. Netflix is pursuing growth through live events, gaming, and advertising, with plans to expand its ad-supported offering to 15 markets while adjusting its workforce by about 6% to improve margins. Investors may want to monitor advertising growth, engagement, and profitability. This article is for informational purposes only and is not investment advice.

Carvana Earnings: Record Sales, Strong Profit, and Insider Share Sales
Carvana reported third-quarter net revenue of $8.04 billion, up 42.4% year over year and above the $7.7 billion market estimate. Retail units sold reached a record 217,385, an increase of 39.4%. Net income rose to $483 million, while adjusted EBITDA reached a record $800 million, reflecting gains in both revenue and profitability.
Management expects full-year 2026 adjusted EBITDA to reach the upper end of its $2.7 billion to $3.0 billion range. Needham maintained its Buy rating, named Carvana a top pick in transportation technology, and set a $100 price target. Strong results and guidance have drawn investor attention, though continued performance will depend on sales, margins, and operating costs.
Insider transactions are also on investors’ radar. A regulatory filing indicates that CFO Mark Jenkins planned to sell 63,800 shares on November 2, 2026, valued at approximately $4.35 million. Since August, he has planned sales totaling 191,300 shares. An executive share sale alone does not determine a company’s outlook; investors may also consider earnings, cash flow, and future guidance. This article is for informational purposes only and is not investment advice.

FCEL Stock: Data Center Opportunity, Manufacturing Costs, and Lawsuit Risk
FuelCell Energy (ticker: FCEL) provides fuel-cell power solutions. Growing electricity demand from AI data centers could create new business opportunities, while proposed pauses on new data center approvals in some areas have raised concerns about project timelines. A 75-megawatt power project may be affected, and FCEL shares recently fell as much as about 17% in a single session amid policy concerns.
FCEL signed an agreement with Fit Energy to provide up to 380 megawatts of fuel-cell power solutions. Its backlog is approximately $3.6 billion, with about 97% of its sales pipeline related to data centers. The company also drew the second installment under a $49 million financing arrangement backed by an export credit agency, supporting a green energy project and clean-energy exports. Recent leadership changes include Matthew Latino becoming CFO, digital infrastructure executive Peter Hopper joining the board, and John Dansby leading manufacturing scale-up. Converting orders into revenue will depend on production capacity, costs, and project execution.
FCEL reported third-quarter revenue of about $33 million, down approximately 29% year over year, and a net loss of roughly $45.3 million. Product costs and manufacturing overhead for the Fit Energy agreement exceeded the contract pricing, resulting in an approximately $17 million contract impairment charge. Securities class-action allegations concern disclosures about manufacturing capacity and costs; the case remains in the legal process. The deadline to seek appointment as lead plaintiff is November 10, 2026. FCEL’s growth opportunities come with execution, financing, and litigation risks. This article is for informational purposes only and is not investment advice.

Democratic Party's AI Regulation Push Revealed: Plans for Intensive Legislation and Strict Scrutiny of Tech Giants

PFE Stock: Pfizer’s Q3 2026 Earnings, Business Strategy, and Dividend Outlook
PFE is the New York Stock Exchange ticker for Pfizer Inc. In the third quarter of 2026, Pfizer reported revenue of $16.58 billion and adjusted earnings per share of $0.87, both above market expectations. The company raised its full-year revenue outlook to $62 billion–$64 billion and its adjusted EPS guidance to $2.95–$3.05, pointing to stronger performance than previously expected.
Although demand for COVID-related products continues to decline, Pfizer’s non-COVID business is growing. Third-quarter sales reached $720 million for the cancer drug Padcev and $2.52 billion for Eliquis, up 25% year over year. Revenue from newer and acquired products rose 32%. Pfizer is expanding its oncology pipeline, entering the weight-loss treatment market through its acquisition of Metsera, and targeting approximately $9.7 billion in net cost savings by 2029. Cecile Guegan has also taken over as chief financial officer.
Investors are also watching Pfizer’s dividend and legal developments. The company declared a cash dividend of $0.43 per share, with an ex-dividend date of November 6, 2026. Analysts raised some earnings estimates and price targets following the quarterly results. Pfizer also faces ongoing legal scrutiny related to statements about COVID vaccine safety, while its subsidiary Mylan has sued Novo Nordisk over generic-drug patent issues involving Wegovy. Pfizer’s outlook depends on new-product growth, cost savings, patent matters, and litigation developments. This article is for informational purposes only and is not investment advice.

South Korea’s GOPAX halts crypto trading, withdrawals after hacking threat
Bhutan: A royal decree opens the future central bank's reserves in Gelephu to cryptocurrencies

AI Begins to Shake Google's Search Advertising Business Behind $500 Billion Market Value Erosion
What is the real challenge for South Korean exchanges now that the regulatory framework is in place?
What Is TLT? Long-Term Treasury Bonds After the Midterm Election
Former FBI Agent Pleads Guilty to Stealing $2.5M in Crypto From 35 Investigations
Mr&强 Discusses Bitget Forex Trading Upgrade with Up to 2000x Leverage
Breaking Down Bitcoin Trends: What Determines the True Value of L1?
Chainalysis Attack More Serious Than Expected: User Password Hashes and Active Tokens Leaked
U.S. Stocks Plunge $2.8 Trillion Overnight! Top Silicon Valley VC Reveals: 90% of Open Source Model Spending Goes to China
StockFi: Connecting U.S. Stock with the On-Chain Ecosystem to Reshape Asset Circulation
Cassius Cuvee on Market Euphoria, High Leverage, and How to Stay in the Game
Secret Network lost 4.67 million dollars due to a cross-chain vulnerability, and the attack went undetected for seven days
CoW Swap released a report on the attack incident, stating that the domain was hijacked for several hours, resulting in an estimated loss of 1.2 million dollars
A user lost approximately 50 million dollars in a single transaction due to slippage, and the founder of Aave stated that the interface had issued multiple warnings
Ethereum software bug triggers emergency fixes across major layer-2 networks
Kraken Owner Invests in Altcoin, Considers Further Purchases. You Should Recognize Him
Stablecoins offer sub-cent payments, Armstrong says, as critics flag risks


